Key Events This Week: FOMC Minutes, Umich Sentiment, and Central Bank Speeches
ZeroHedge ·
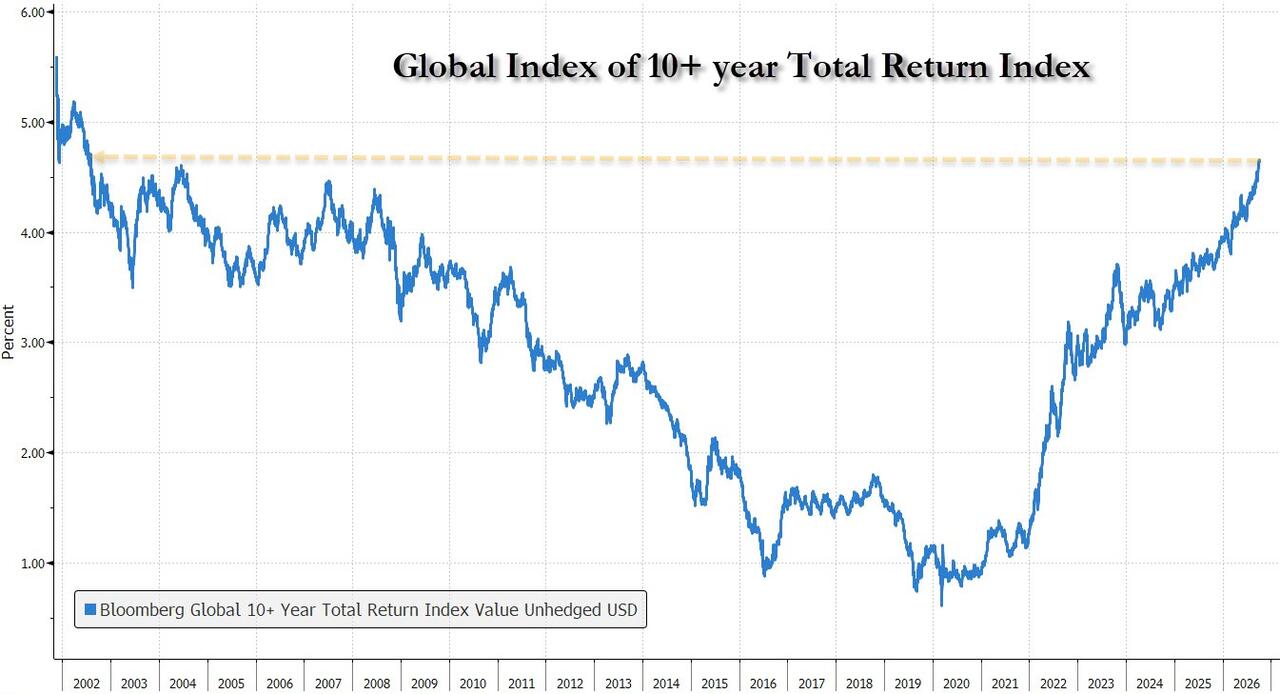
Global bond markets remain on high alert as 10-year yields hit their highest levels since 2022, shifting market attention heavily toward central banks this week. The key highlights include the release of the September FOMC meeting minutes on Wednesday and the ECB meeting account on Thursday, alongside numerous central bank speeches. On the data front, the week follows a crucial September employment report where headline payrolls rose by just +29k, missing the expected +133k, while private payrolls increased by +46k compared to the forecasted +127k. In addition, prior months saw 60k in downward revisions, and average hourly earnings edged up by only +0.1%. Nevertheless, DB economists point out that broader labor market metrics remained resilient, with the unemployment rate ticking up slightly to 4.175% and labor force participation rising to 61.8%. Consequently, DB expects two additional 25bp Fed rate hikes over the upcoming quarters, while markets price in another 86bps of tightening over the next 12 months.
AI 시장 분석
This week's market is closely monitoring interest rate volatility, focusing on the release of the September FOMC minutes, the ECB meeting minutes, and speeches by multiple regional Fed presidents. In last Friday's September non-farm payrolls report, headline employment increased by 29,000, falling short of expectations, but the unemployment rate remained stable at 4.175%. Accordingly, the market is pricing in the possibility of additional Fed rate hikes, heightening tension in the bond market.
상승 영향
- Banks — Rising global government bond yields and the possibility of additional Fed hikes induce wider loan-deposit spreads, acting as a direct positive factor for the profitability of the banking sector.
- Bonds — Higher government bond yields and increased market volatility heighten preference for safe assets, highlighting bond purchase demand and yield attractiveness.
하락 영향
- Growth Stocks — Global 10-year Treasury yields recorded their highest level since 2022, increasing valuation burdens on future cash flows of tech and growth stocks due to rising discount rates.
- Real Estate — The persistently high level of government bond yields and rising funding costs directly stimulate concerns over shrinking demand and loan defaults in the real estate market.
DYAX 전담 분석
The tension in the bond market and the 10-year Treasury yield breaking its highest level since 2022 are increasing funding costs in global financial markets, adding to valuation pressures across the stock market. If the Fed maintains its hawkish stance amidst mixed employment data, downward pressure on growth stocks and the real estate market could increase.
Depending on the upcoming FOMC minutes and additional inflation and employment data, further rises in Treasury yields could strengthen a growth stock-led bearish scenario. Conversely, confirmation of a rate freeze stance could act as momentum for a rebound in bonds and growth stocks. Key monitoring indicators are the US 10-year Treasury yield and Fed officials' remarks on the rate hike path.
AI가 생성한 분석으로 투자 자문이 아닙니다.
DYAX Investor Sentiment
Bullish (Long) 57% · Bearish (Short) 43%
421 participants
Related News
- UKMTO Receives Incident Report in Strait of Hormuz Involving Tanker
- Explosions Heard North of Riyadh According to Saberen News
- ECB Official Warns France Faces Rate Pressure Without Fiscal Reform
- Houthis Seize Yemen Parliament Speaker's Home and Sever Critical Taiz Supply Route
- Iran Rejects Talks Amid Regional Tensions and Recent Reports of Attacks
- Explosions Reported in Riyadh and Chanel Posts Strong Revenue Growth
