Fitch Downgrades Paramount Skydance Debt to Junk as Mega-Merger Closes
ZeroHedge ·
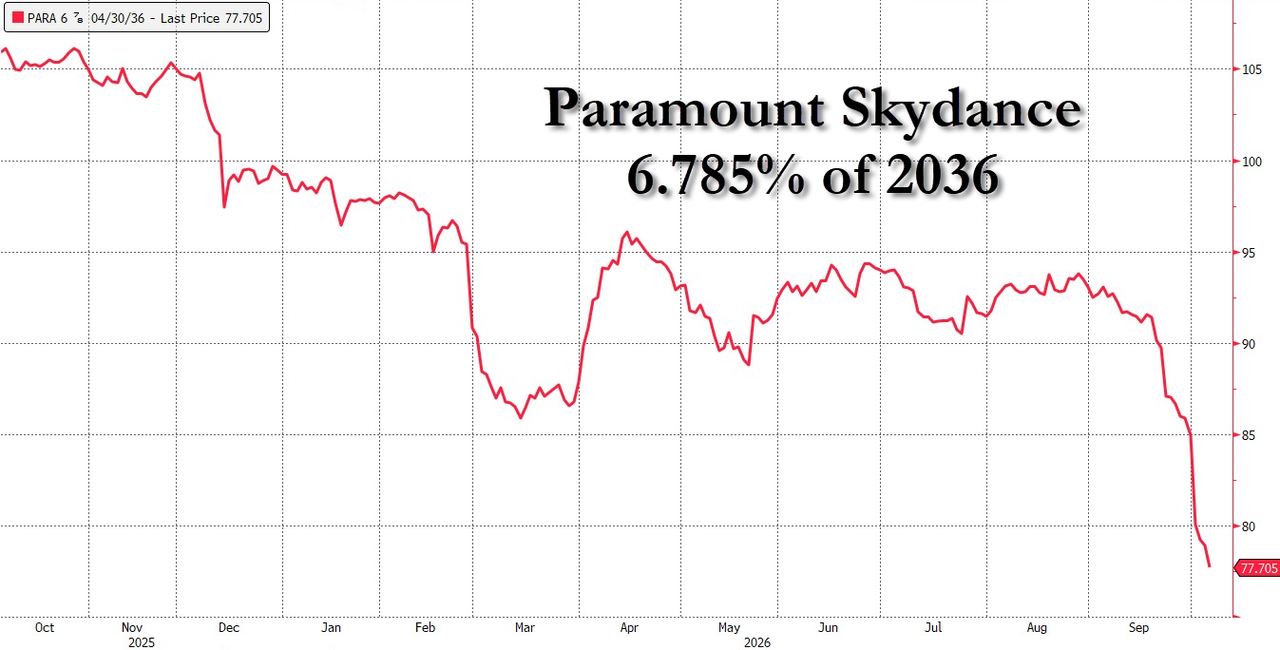
Following the official completion of the 110 billion dollar Warner Bros. Discovery acquisition, Fitch Ratings downgraded the issuer ratings of Paramount Skydance and WBD deeper into junk territory to BB from BB+, highlighting heavy leverage and substantial integration risks. The decision delivered a severe blow to legacy senior unsecured notes, which were cut to BB- with an RR5 recovery rating, implying a paltry 11% to 30% recovery expectation in default scenarios. Meanwhile, legacy WBD unsecured debt was slashed to B+/RR6, signaling near-total potential losses. The market reaction was swift and brutal. Paramount's 6.875% notes due 2036 cratered to an all-time low of 77.7, shedding roughly 14 points over a three-week span and pushing yields to approximately 10.6%. This dramatic rout stems from capital structure subordination, as roughly 57 billion dollars in newly prioritized secured debt now sits ahead of the unsecured holders in the newly combined enterprise.
AI 시장 분석
Fitch downgraded Paramount Skydance's credit rating to BB following the completion of its $110 billion merger with Warner Bros. Discovery. Notably, the recovery rate for legacy unsecured bonds plummeted to 11-30%, sending the 2036 maturity bonds to an all-time low of 77.7. With approximately $5.7 billion in senior secured notes taking priority over unsecured bonds, bondholder risk has surged dramatically.
하락 영향
- Entertainment — The completion of the $110 billion merger highlighted a massive debt burden of $87.5 billion and integration risks, leading to a downgrade to junk status.
- Bond Market — As senior secured notes were placed ahead of existing unsecured bonds, Paramount's legacy unsecured bond prices crashed to an all-time low and recovery rates plummeted.
DYAX 전담 분석
The merger has resulted in a combined company total debt of $87.5 billion, creating massive financial leverage and integration risks. As a large volume of senior secured notes was prioritized over existing unsecured notes, the principal recovery prospects for legacy unsecured bonds were severely impaired.
The bullish scenario involves cash flow improvement through restructuring and synergy creation by the merged entity, while the bearish scenario entails further credit rating downgrades and intensifying debt repayment pressures. Investors should monitor the merged entity's profitability metrics and refinancing schedule going forward.
AI가 생성한 분석으로 투자 자문이 아닙니다.
DYAX Investor Sentiment
Bullish (Long) 39% · Bearish (Short) 61%
282 participants
Related News
- RBI Elevates Repurchase Rate by 25bps to 5.50% in Unanimous Vote, Shifts Stance to Calibrated Tightening
- Indian RBI Raises Interest Rate to 5.50%
- US Seeks Info from Russia and Coordinates Globally
- Iran Deputy Foreign Minister Meets Envoys from India, Japan, and Spain
- Monetary Authority of Singapore to Release Quarterly Policy Statement on October 14th
- China's September Foreign Exchange Reserves Decline to $3.400T
